LLC Tax Reporting For Texas owners
Member count or an accepted election has already pointed at a federal report. The sheet this state can still ask for sits in a different pile, and that pile is what this page walks.
See the federal report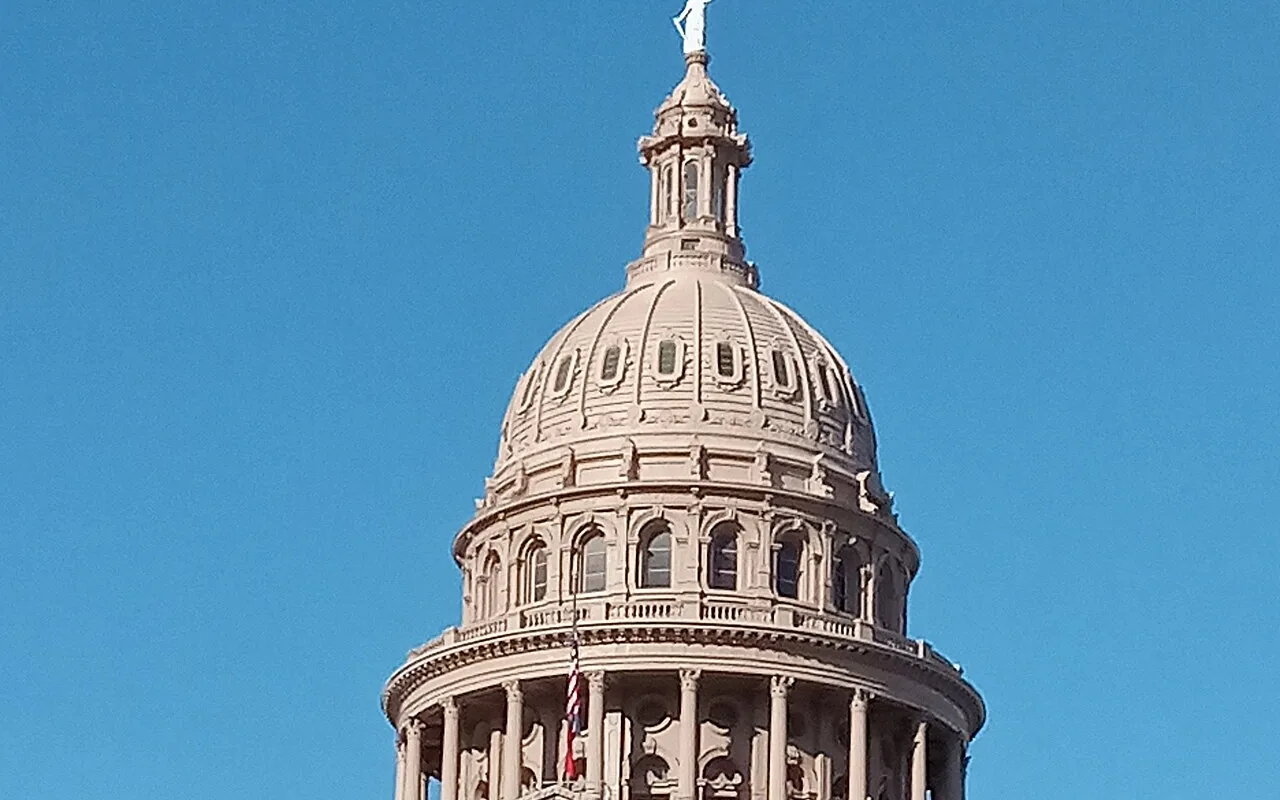
The practice sits in Dallas.
Steven Palmieri is the Tax CFO, and the practice that reads your file sits in Dallas. A video call is how the company file gets there, from a shop in Houston, from Austin, from the Hill Country, from along the Gulf, or from up in the Panhandle. Your county does not hold a second office of this practice. In the photograph, scaffolding covers the capitol, and that building is not where owners sit down with us.
A shop nowhere near Dallas or Fort Worth is still this page's reader, and we are all Texans once the company is formed in this state or does business here. Miles on the road at night do not change the member count, the election, or the bank picture that crosses the same screen. Every other page on this address stays with the federal choice. Only here do we walk the sheet the state can still ask for after that federal choice already has a name.
One owner, two owners, an accepted S election, an accepted C election, or a year when the bank stayed quiet: those questions live on the federal pages. None of those pages quotes a rate for this state, and none of them names a city. Hand those pages the acceptance letter, or tell us the election drawer is empty. Hand this page the letter that has the state's name on it.
CupWithSoda19 made the capitol photograph while crews worked the front, and released it under CC BY-SA 4.0. Scaffolding in the frame belongs to the year of that photograph. It says nothing about construction in the year you bring the file.
Who owes the privilege report.
Call it a privilege tax, which is the Comptroller's name for the franchise tax on a taxable entity formed in Texas or doing business in Texas. Publication 98-806 is the walkthrough, and its list runs through corporations, limited liability companies with one owner, series companies, banks, S corporations, partnerships, and the further entities that same publication names. Someone who never formed a company is usually missing from the list. A limited liability company that has only one member is still on it.
Owners who are all natural persons, with no entity sitting beside them, usually leave a general partnership off this report. Recast that partnership as a limited liability partnership and the report pulls the partnership back on. Passive entities belong on the do-not-file list, and the year's facts are how we read that label. Initials printed on the certificate of formation settle nothing by themselves. Rule 3.586 is where Publication 98-806 sends a reader who wants examples of doing business in Texas, and each example gets held up to this company's own facts instead of a guessed border.
Member count, or an election the government already accepted, is what told the federal pages which report follows. Nothing written here overwrites that federal answer. Federal income tax can treat the company as disregarded while this state still wants a sheet of its own. Employment tax already showed that kind of split on the federal pages. The state sheet is one more split, and a different office is the one that reads it.
Under the line, a sheet remains.
Set the 2026 report year beside the 2027 report year and the no-tax line is the same figure, annualized total revenue of 2,650,000 dollars. At or under that figure the privilege tax itself is zero, and the tax report stays unfiled. The information filing can stay open all the same. Public information moves on Form 05-102, and ownership information moves on Form 05-167. Unless the skip list names your company, one of those two forms is still the one that gets signed. Report years from 2024 forward retired the old no-tax-due report, so that older paper is not the filing in front of you now.
Look back at the 2024 report and the 2025 report, where the compensation those years would deduct could not pass 450,000 dollars, and where no tax was due in either year when annualized total revenue sat at or under 2,470,000 dollars. Keep both of those figures inside 2024 and 2025, because neither one is a 2026 number. A page that folds the rows together would hand the owner a threshold from the wrong year.
Sell goods at retail or at wholesale and the 2026 and 2027 reports put 0.375 percent on that margin. Do the work as services, rather than across a retail counter, and those same reports put 0.75 percent on the margin. Compensation the report will let you deduct stops at 480,000 dollars in 2026 and in 2027. Annualized total revenue at or under 20 million dollars opens the EZ computation, which applies 0.331 percent and gives the margin deductions up. Cross above that line, or decide you will take a margin deduction, and the long form is the path you are on.
Four computations sit on the publication's list once the long form is the one you must use: 70 percent of total revenue, total revenue after cost of goods sold comes off, total revenue after compensation comes off, or total revenue after 1 million dollars comes off, and that million-dollar subtraction has been in the statute since the start of 2014. Section 171.1011 of the Tax Code is the list of exclusions, and those exclusions come off whatever the federal return already called revenue, before this report treats the remainder as its starting total. Cost of goods sold here is aimed mostly at tangible personal property and real property, so a company that sells only services will often find none it can use, aside from the industry exceptions written in section 171.1012. Wages that show up on a W-2 can enter the compensation deduction, and amounts paid on a 1099 stay outside it. Once a margin is chosen, apportionment uses Texas gross receipts, and this page prints no sample of that math taken from a living return.
Late sheets after May.
Mark May 15, because that is the report day, and a weekend or a holiday moves the mark to the next business day. Come in after the marked day and the report, standing alone, is a 50 dollar charge counted before anyone turns to the tax. Tax still open during the first 30 days after the due date picks up an extra 5 percent of the tax. Stay out past that 30th day and the extra becomes 10 percent of the tax. After 61 days the unpaid balance starts to draw interest, and the percent to apply is the one printed on the Comptroller interest page, which this page refuses to copy.
Ask for more time with a timely payment and the figure is generally 100 percent of the prior-year tax, or 90 percent of the tax this year will actually owe. The first annual report after an entity becomes subject to the tax cannot lean on that 100 percent option. A payer who is not required to pay electronically reaches November 15 through Webfile or through Form 05-164. Pay 10,000 dollars or more during the previous state fiscal year and the entity is on electronic payment, with August 15 as the first extended date and November 15 as the second. At 500,000 dollars or more, more time is requested by sending the TEXNET payment on time under payment code 13080, and that payment stands in so Form 05-164 does not also have to go. The hour that still counts a large TEXNET payment as on time is written on the live instruction, and the hour stays on that instruction.
Count 60 days after the entity no longer has sufficient nexus, and that is when the final report is due. Closing the company, or ending the tie to this state, is the owner's own decision. Both the final report and the certificate of account status from the Secretary of State belong in that closing. We read the close instructions that are current before we say which paper goes first, because an order remembered from an older year would be a fiction.
Leave the information report unfiled and the statute warns that the right to sue or to defend in a state court can sit at risk, and that officers and members can be exposed on certain debts. Four sections carry the warning, and you read them in code order, 171.251, then 171.2515, then 171.252, then 171.255, because that is where court rights and certain debts get named. Financial institutions follow a different pair of sections, 171.259 and 171.260. Change the officers after the filing and the change waits for the next annual report, unless what you are fixing is an error and you amend. The registered agent travels on a filing of its own to the Secretary of State, and these reports are not where that name gets typed.
What your books must hold.
Building the privilege report out of the books is tax work. Someone has to be allowed to sign before a report on the statements can go out, and that signed paper is a different assignment from the privilege report this page is walking. What you sign here is not an opinion on those statements. The disclosures page already writes out the refusal to sign that kind of opinion, so this page will not lecture the point a second time.
Imagine a made-up company, never a return that belongs to a living owner, sitting under 2,650,000 dollars and still signing the information report in a year when the tax is zero. That owner signs Form 05-102 or Form 05-167 even in the quiet year, unless the skip list already names the company. Publication 98-806 leaves several names off those two forms, among them passive entities, exempt entities, a company with no organization in Texas and no tie to Texas, and a qualifying new veteran-owned business through its first five years.
Figures for revenue on this report start from the federal return. Disagree with the federal return about that revenue and the disagreement is representation work, which this address does not file. A protest, or a suit over the state tax that needs a lawyer, stays with the lawyer. Tell us about the letter and we will name the pile it belongs in. We will not borrow a title so we can work the other pile.
Research-credit rules on this report changed for periods that start in 2026, and the franchise home page is where that change is pointed out. In the year the file arrives we follow the page that is live then. A frozen summary of the credit does not get written onto this address.
Collecting on a taxable sale.
Ring up a taxable sale and set 6.25 percent of the price aside, because that slice is the state's sales tax before any local government adds a cent. Three local bodies can add their own sales-tax slice, the city, the county, and a transit district, and the slices they add are stopped at 2 percent combined. Put state and local on the same sale and the stack cannot pass 8.25 percent. The rate follows the place, so the address gets looked up on the day the sale happens, and a city's rate is not a number we keep in memory.
After a permit is approved, the letter that comes back says whether the filing rhythm is each month or each quarter. A monthly report leaves on day 20 of the month that follows. Land that day on Saturday, on Sunday, or on a legal holiday, and the report moves to the next day the office is open. File by the due day and pay by that same day under the permit, and the seller may keep half of one percent of the tax as the reward for being on time. Before anyone discusses the tax, a late report is a 50 dollar charge of its own. Inside a window of 30 days after the sales-tax due day, money that arrives picks up five extra percent of the tax owed. After that window shuts, money still missing picks up ten extra percent of the tax owed. A past-due sales balance begins to draw interest after 61 days, and the rate for that interest stays on the interest page.
On every other page of this address the open question is still the federal report. A letter from this state does not hand the election a new name, and a federal report that already has a name does not answer the state letter. Bring the pair of them. We will sort each letter into its pile, and we will say which choice can still move while the year remains open.
Name the state letter and the year
You will be talking to the Steven Palmieri practice.